Table of Contents
In international trade, the payment terms written into a Letter of Credit (LC) can have a direct effect on when an exporter receives money and how long an importer has to arrange payment. Two common structures are LC at Sight and Usance LC.
The simplest distinction is timing: a sight LC is available for payment at sight when there is a complying presentation, while a usance or deferred-payment LC provides for payment at a future maturity specified in the credit.
What Is an LC at Sight?
An LC at Sight is a documentary credit under which payment is available at sight, subject to the terms of the credit and a complying presentation of the required documents.
Under UCP 600, a credit must state whether it is available by sight payment, deferred payment, acceptance, or negotiation. Banks examine the documents presented to determine whether they constitute a complying presentation.
What Is a Usance LC?
A Usance LC, also called a deferred-payment LC in many trade contexts, provides for payment at a future date or maturity stated in the credit. The tenor may be expressed in terms such as 30, 60, 90, or 120 days, depending on the agreed transaction.
LC at Sight vs Usance LC: Quick Comparison
| Feature | LC at Sight | Usance LC |
|---|---|---|
| Payment timing | At sight after a complying presentation | At a future maturity stated in the credit |
| Exporter cash flow | Generally earlier payment | Payment is deferred |
| Importer cash-flow period | Less time before payment | Agreed credit period before maturity |
| Documents | Must comply with the LC terms | Must comply with the LC terms |
| Financing considerations | May reduce the seller’s waiting period | May create a financing requirement for the seller |
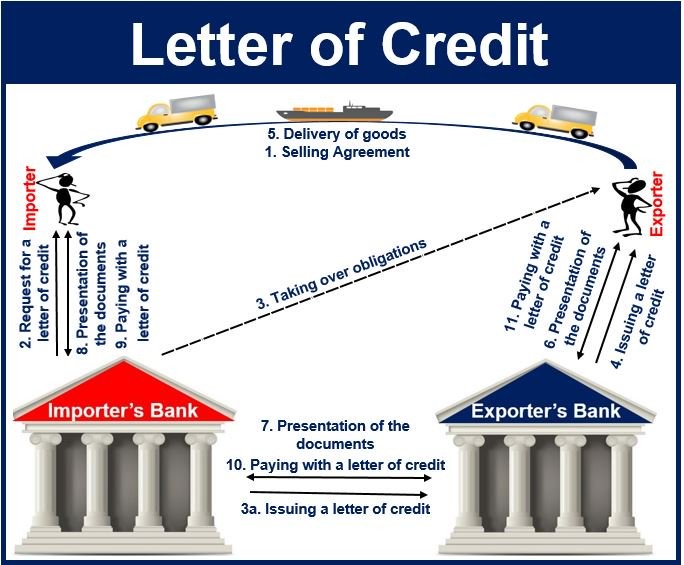
How an LC Payment Works
- The buyer and seller agree on the commercial contract and LC terms.
- The issuing bank issues the documentary credit according to the agreed conditions.
- The advising bank advises the credit to the beneficiary.
- The exporter ships or performs according to the credit.
- The exporter presents the required documents within the stated time and place.
- The relevant bank examines the presentation against the credit terms and applicable rules.
- If the presentation is complying, payment is made according to whether the credit is available at sight or on a deferred basis.
What Is a Complying Presentation?
This is an important part of any documentary-credit transaction. ICC guidance explains that a complying presentation is one that follows the terms and conditions of the credit, the applicable UCP 600 provisions, and international standard banking practice.
UCP 600 Article 14 states that the issuing bank, confirming bank if any, and nominated bank acting on its nomination examine a presentation on the basis of the documents. The rules provide a maximum of five banking days following presentation for that examination.
LC at Sight: Practical Considerations for Exporters
- Check every document requirement before shipment.
- Make sure names, quantities, dates, ports, and document references are consistent with the credit.
- Confirm the latest presentation date and place.
- Understand which bank is nominated to honour, negotiate, or handle the documents.
- Allow time to correct documentation issues before the presentation deadline where possible.
Usance LC: Practical Considerations
- Confirm the exact tenor and the event from which the tenor is calculated.
- Check whether the credit is by deferred payment, acceptance, or another availability structure.
- Consider the financing cost created by waiting for maturity.
- Agree clearly who bears bank charges, discounting costs, and financing expenses.
- Check whether the buyer’s market normally uses 30, 60, 90, or another agreed tenor.
LC at Sight vs Usance LC for Indian Exporters
For an Indian exporter, the choice between sight and usance terms can affect working capital, pricing, bank charges, and the timing of funds received after shipment. The commercial decision should therefore be considered together with the product price, freight terms, financing cost, and buyer relationship.
If you are new to exporting from India, you can also read our guide to starting an export business from India and our IEC Code guide for Indian exporters.
Common Mistakes With LC Payment Terms
- Assuming an LC guarantees payment regardless of documents.
- Ignoring the exact presentation deadline.
- Using old document templates without checking the current credit terms.
- Failing to clarify the usance tenor and its starting point.
- Comparing a sight LC and usance LC without considering financing and bank charges.
Frequently Asked Questions
What is the main difference between LC at Sight and Usance LC?
The main difference is payment timing. A sight LC is available for payment at sight subject to a complying presentation, while a usance LC provides for payment at a future maturity.
Is Usance LC the same as deferred payment LC?
In common trade usage, usance LC is often used to describe deferred-payment or time-payment arrangements. The exact availability wording in the credit should always be checked.
How long can a Usance LC be?
The tenor is agreed by the parties and stated in the credit. Common examples include 30, 60, 90, and 120 days, but the actual term depends on the transaction.
Does an LC guarantee payment automatically?
No. Payment depends on the credit terms and a complying presentation. Banks examine documents under the applicable rules; they do not simply guarantee payment regardless of discrepancies.
Conclusion
LC at Sight and Usance LC serve different cash-flow needs. Sight payment generally gives the exporter earlier access to funds, while usance terms give the importer an agreed period before payment falls due. The exact wording of the credit matters, so exporters and importers should review the LC with their bank or trade-finance professional before shipment.
Reference: International Chamber of Commerce, UCP 600 rules for documentary credits.
Related Articles